Yes. A property management company can be sued when a tenant, visitor, or other individual is injured at a property it manages. Even when the property owner or an outside contractor is responsible for the underlying condition, the property manager may face allegations that its negligence contributed to the injury.
These claims can create a significant insurance problem. General Liability (GL) policies commonly exclude claims arising from professional services, while many Errors & Omissions (E&O) policies exclude Bodily Injury and Property Damage.
Without the appropriate coverage in both policies, a property management company could find itself facing a lawsuit that neither policy adequately addresses.
How Can a Property Management Company Be Held Liable for a Tenant’s Injury?
Property managers have responsibilities that extend beyond collecting rent and coordinating leases. Their professional services often include arranging maintenance, responding to complaints, inspecting properties, and selecting or overseeing outside contractors.
Consider several examples:
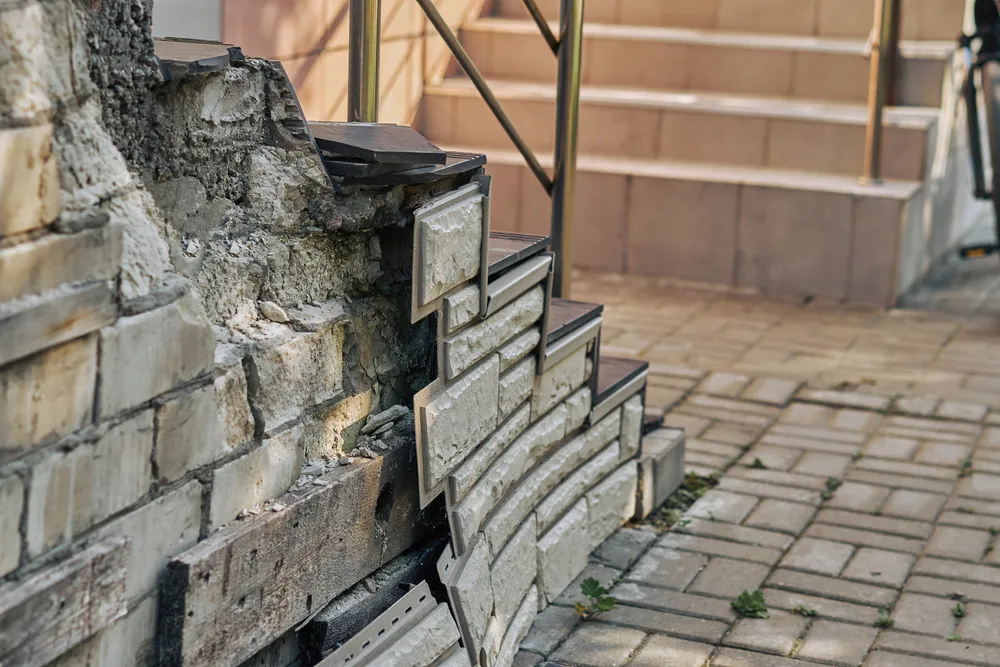
- Slip and Fall: A tenant reports a damaged staircase, but the property manager allegedly fails to arrange timely repairs. The tenant subsequently falls and suffers serious injuries.
- Dog Bite: A property manager allegedly fails to address repeated complaints about a dangerous dog, and another tenant or visitor is injured.
- Negligent Contractor Selection: A property manager hires an outside contractor who performs defective repairs, resulting in an injury.
- Failure to Address a Hazard: A property manager receives reports of a dangerous condition but allegedly fails to take appropriate action before someone is injured.
In each situation, the property owner or contractor may share responsibility. However, that does not necessarily prevent the injured party from naming the property management company in a lawsuit.
Whether the property manager is ultimately liable depends on the facts, applicable law, contractual responsibilities, and whether the manager owed and breached a legal duty.
Even when the property manager successfully defends the allegations, the cost of legal representation can be substantial.
Why General Liability Insurance May Not Cover the Claim
General Liability insurance is an essential component of a property management company’s insurance program. It typically addresses certain claims involving bodily injury, property damage, and personal or advertising injury, subject to policy terms and exclusions.
However, many GL policies contain professional services exclusions.
These exclusions can restrict coverage for injuries or damages arising from the insured’s performance of, or failure to perform, professional services.
For a property management company, that distinction is especially important.
Consider a tenant who suffers an injury after a property manager allegedly fails to arrange repairs to a known hazard.
The injury itself involves Bodily Injury, an exposure commonly associated with General Liability insurance.
However, the allegations against the property manager concern its failure to properly perform professional property management services.
Depending on the GL policy’s wording, the insurer may determine that the professional services exclusion applies.
This creates an important distinction: Just because a lawsuit involves Bodily Injury does not mean it is covered by General Liability insurance.
Why Many E&O Policies May Not Cover the Claim Either
Errors & Omissions insurance is designed to address certain claims arising from mistakes, negligence, or failures in the performance of professional services.
However, many real estate E&O policies contain broad Bodily Injury and Property Damage exclusions.
For example, an E&O policy may exclude:
Bodily Injury or Property Damage
Some policies provide limited exceptions for specific circumstances, such as injuries occurring during an open house or involving a lockbox.
Others provide limited Bodily Injury or Property Damage coverage through endorsements, sometimes with sublimits significantly lower than the policy’s overall liability limit.
A property management company might purchase a $1 million E&O policy, for example, only to discover that the policy provides $25,000, $50,000, or $100,000 for certain Bodily Injury claims, or excludes them entirely.
The actual protection depends on the wording of the policy, its endorsements, and any applicable sublimits.
This is why reviewing only the declarations page is insufficient.
A $1 million E&O limit does not necessarily mean the company has $1 million available for a lawsuit involving a tenant’s injury.
The Coverage Gap Between GL and E&O
The greatest concern arises when the two policies contain exclusions that leave the same claim uninsured.
Consider the following scenario:
A tenant falls through a deteriorated deck at a rental property. The property manager had previously received complaints about the deck but allegedly failed to arrange an inspection or repairs.
The tenant sues both the property owner and the property management company.
The property manager submits the lawsuit to its GL insurer, which may invoke a professional services exclusion because the allegations concern negligent property management.
The property manager then submits the lawsuit to its E&O insurer, which may invoke its Bodily Injury exclusion.
The result could be a substantial coverage gap.
Neither insurer’s decision is automatic. The allegations, policy wording, applicable law, and other circumstances determine whether coverage exists. Nevertheless, this example illustrates why property management companies need their GL and E&O policies to work together.
What Is Contingent Bodily Injury and Property Damage Coverage?
Contingent Bodily Injury and Property Damage coverage is designed to address certain claims involving physical injury or property damage arising from the insured’s professional services when other applicable insurance does not respond.
For property managers, this can be one of the most important provisions in an E&O policy.
Unlike traditional real estate E&O forms that broadly exclude Bodily Injury and Property Damage, specialized property management E&O coverage may provide protection for allegations involving negligent maintenance coordination, contractor selection, or other covered professional services.
However, the provision’s wording is critical.
Property managers should determine:
- Whether the policy provides coverage for Bodily Injury and Property Damage arising from professional services.
- Whether the coverage is subject to a separate sublimit.
- Whether the policy requires the insured to maintain General Liability insurance.
- Whether coverage is contingent upon another insurance policy being unavailable or inapplicable.
- Whether defense expenses reduce the available liability limit.
These provisions can significantly affect the amount of protection available when a claim occurs.
How Does PBI Group’s E&O Policy Address Bodily Injury and Property Damage?
PBI Group’s specialized real estate E&O program, underwritten by Palomar Specialty Insurance Company, includes an endorsement designed to address Contingent Bodily Injury and Property Damage Claims arising from covered professional services.
The policy defines these claims, in relevant part, as:
“any Claim alleging Bodily Injury or Property Damage”
The definition further requires that the claim result from an insured’s act or omission in performing Real Estate Professional Services, that no other policy be applicable, and that the act or omission be a proximate cause of the injury or damage.
This is an important distinction from E&O policies that provide no meaningful exception to their Bodily Injury and Property Damage exclusions.
Under the PBI Group program, qualifying contingent claims may be covered subject to the policy’s overall liability limits, rather than a separate, substantially reduced Bodily Injury or Property Damage sublimit.
Why PBI Group Also Requires General Liability Insurance
The PBI Group program is designed to work alongside a properly structured General Liability policy, not replace one.
The E&O endorsement requires the insured to maintain GL insurance with specified limits and coverage components, including Premises/Operations and Products/Completed Operations liability.
This requirement is particularly important for property management companies because the exposures associated with managing rental properties can involve both traditional GL liability and professional negligence.
For example, a contractor’s work may lead to a property damage or injury claim that implicates General Liability coverage, while separate allegations against the property manager may concern negligent selection or supervision of that contractor.
The two policies address different aspects of the company’s potential liability.
Why Products/Completed Operations Coverage Matters
Property management companies should pay particular attention to whether their GL policy includes meaningful Products/Completed Operations coverage.
The Palomar sample policy includes a provision limiting Contingent Bodily Injury and Property Damage Claims to a $250,000 aggregate when the insured maintains GL insurance that does not include the specified Premises/Operations and Products/Completed Operations coverages.
That limitation is part of, not additional to, the policy’s overall aggregate limit.
This illustrates why purchasing the least expensive GL policy without examining its exclusions and coverage components can create problems beyond the GL policy itself.
A property management company’s GL coverage can directly affect the protection available under its E&O policy.
What Should Property Managers Look for When Reviewing Their Insurance?
Property management companies should not assume that purchasing both GL and E&O automatically eliminates coverage gaps.
The policies need to be evaluated together.
On the General Liability policy, review the professional services exclusion, the scope of Premises/Operations and Products/Completed Operations coverage, and any exclusions involving managed properties, contractors, maintenance operations, or other relevant exposures.
On the E&O policy, review the Bodily Injury and Property Damage exclusions, any exceptions restoring coverage, applicable sublimits, the definition of professional services, and requirements involving underlying General Liability insurance.
It is equally important to examine whether defense expenses reduce the limits available to pay damages.
A policy may provide a substantial headline liability limit but considerably less protection for the particular allegations a property management company is most likely to encounter.
Does Requiring Property Owners and Contractors to Carry Insurance Eliminate This Exposure?
No.
Requiring property owners and contractors to maintain appropriate liability insurance is an important risk management practice. Property managers should also consider additional insured requirements and contractual indemnification provisions where appropriate.
However, these measures do not guarantee that the property management company will be protected against every lawsuit.
A tenant may allege that the property manager independently failed to respond to complaints, arrange repairs, or exercise reasonable care in selecting or supervising a contractor.
Even if another party ultimately bears responsibility, the property management company may still incur significant defense expenses.
Additionally, another party’s insurance may contain exclusions, insufficient limits, or restrictions affecting whether the property management company qualifies for coverage.
Requiring others to carry insurance is not a substitute for ensuring that the property management company’s own GL and E&O policies adequately address its professional exposures.
Frequently Asked Questions
Does property management E&O cover tenant slip-and-fall claims?
Some specialized E&O policies provide coverage for qualifying Bodily Injury claims arising from negligent professional property management services. Other policies exclude these claims entirely or provide only limited coverage. The circumstances and policy wording determine whether coverage applies.
Does General Liability cover negligent property management?
Not necessarily. GL policies commonly contain professional services exclusions that may apply when the alleged negligence involves property management duties. The specific wording of the exclusion is important.
Does E&O cover injuries caused by outside contractors?
Coverage may be available when the property manager is accused of negligent selection, hiring, or supervision of an outside contractor, provided the allegations fall within covered professional services and satisfy the applicable policy provisions. The contractor’s own work and liability may be treated differently.
Is $1 million in E&O coverage enough for Bodily Injury claims?
A $1 million E&O policy does not necessarily provide $1 million for Bodily Injury claims. Some policies exclude these claims or impose separate sublimits. Property managers should examine the actual coverage provisions rather than relying solely on the declarations page.
Can a property manager be sued even if the property owner has insurance?
Yes. A property manager can be named in a lawsuit alleging its own negligence, regardless of whether the property owner maintains liability insurance. Whether the owner’s policy provides defense or indemnification to the manager depends on its terms and the circumstances.
Final Thoughts
Bodily Injury and Property Damage claims represent significant exposures for property management companies, particularly when allegations involve maintenance coordination, contractor oversight, or failures to address reported hazards.
Unfortunately, these are also areas where GL and E&O policies can leave substantial coverage gaps.
At PBI Group, we specialize in reviewing the actual policy language behind these exposures. Our real estate E&O program includes Contingent Bodily Injury and Property Damage protection designed to complement properly structured General Liability insurance.
If you manage rental properties, we can review your existing GL and E&O policies to help identify exclusions, sublimits, and potential gaps before a claim occurs.
Coverage descriptions are based on the referenced Palomar Specialty Insurance Company sample policy and PBI Group endorsements. All coverage is subject to the terms, conditions, exclusions, limits, and endorsements of the policy actually issued.